Monitoring the Session

HB 3279

Dutton’s Tax Break Sunset Needs A Constitutional Amendment First

Died in committee

Verdict: Smells

SmellsInitial review
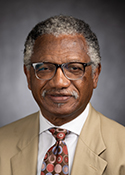
Rep. Harold V. Dutton Jr.DHouse 142
Both charges, and why
New fee, fund, board or appointees

THE TEXT

“The select commission on periodic tax preference review is composed of:”

Bill text, introduced version (I)

The bill builds a new standing commission with appointed members, a chair, a vice chair, staff support and expense reimbursement. The caption says it plainly, so this is honest but still new government.

New fee, fund, board or appointees
Delayed start

THE TEXT

…“preference included in a final report expires on the second anniversary of the date the final report is submitted”…

Bill text, introduced version (I)

The first final report is due December 1, 2026, after the November 2026 election, so the first tax break cannot expire before late 2028. The whole Act also waits on voter approval of a constitutional amendment.

Delayed start

Initial review · graded Oct 20, 2026 · Headline, summary and grade are analysis of the bill text, not a finding about any person · How we grade

Caption

relating to a periodic review and expiration dates of state and local tax preferences.

Caption from analyzed text · version I.

Summary

Named breaks expire two years after a final report. Earliest: late 2028.

The bill creates a select commission of five House members, five senators and the comptroller to review every state tax break and every type of local tax break on a six-year cycle. It touches anyone who benefits from a Texas tax abatement, credit, exemption, appraisal limit or special rate, plus the legislative staff who must support the commission. Any tax break named in a final report expires two years later unless lawmakers renew it, and new or renewed tax breaks after September 1, 2026 must carry an expiration date no more than six years out, all only if voters approve a matching constitutional amendment.

Labels

Labels: ZOMBIE BILL. Died 2 times: 88R HB 953 (Died in committee) and this bill (Died in committee). Checked against 88R only.BACK FROM THE DEAD. Same text as a bill filed before that died: 88R HB 953 (Died in committee). Filed in 2 sessions, counting this one. Checked against 88R only.TRY NO. 2. Filed in 2 sessions: 88R and 89R. Checked against 88R only.NEVER GOT A HEARING. Filed Feb 25, 2025 and referred to the House Ways & Means committee. No public hearing. The bill died.

Receipt

The receipt

89R-HB3279 · 2025-02-25

SOLD BY

ITEM

relating to a periodic review and expiration dates of state and local tax preferences.

WHAT IT DOES

Named breaks expire two years after a final report. Earliest: late 2028.

The bill creates a select commission of five House members, five senators and the comptroller to review every state tax break and every type of local tax break on a six-year cycle. It touches anyone who benefits from a Texas tax abatement, credit, exemption, appraisal limit or special rate, plus the legislative staff who must support the commission. Any tax break named in a final report expires two years later unless lawmakers renew it, and new or renewed tax breaks after September 1, 2026 must carry an expiration date no more than six years out, all only if voters approve a matching constitutional amendment.

CHARGES

[x] NEW FEE, FUND, BOARD OR APPOINTEESanalysis confidence 60%

THE TEXT

“The select commission on periodic tax preference review is composed of:”

Bill text, introduced version (I)

The bill builds a new standing commission with appointed members, a chair, a vice chair, staff support and expense reimbursement. The caption says it plainly, so this is honest but still new government.

[x] DELAYED STARTanalysis confidence 50%

THE TEXT

…“preference included in a final report expires on the second anniversary of the date the final report is submitted”…

Bill text, introduced version (I)

The first final report is due December 1, 2026, after the November 2026 election, so the first tax break cannot expire before late 2028. The whole Act also waits on voter approval of a constitutional amendment.

TOTAL

No fiscal note in the loaded record.

HISTORY

  1. Filed
  2. Read first time
  3. Referred to Ways & Means
FILED UNDER

CORPORATE WELFARE

THE TEXT

“"Tax preference" means an abatement, credit, discount, exclusion, exemption, limitation on appraised value,”…

Bill text, introduced version (I)

The bill puts business abatements, credits and appraisal limits on a review schedule and an automatic expiration clock unless lawmakers renew them.

GOVERNMENT GROWTH UNDER A CONSERVATIVE BANNER

THE TEXT

“five members of the house of representatives, appointed by the speaker of the house of representatives;”

Bill text, introduced version (I)

The bill creates a new select commission with appointed members whose expenses are paid from state funds.

Smells

THANK YOU FOR CHECKING THE RECEIPT

CAMPAIGN PAID FOR BY

CAMPAIGN PAID FOR BY

Donors

Not tied to this bill.

Sources

The author's campaign account only. Own money and internal transfers are separate on the member page.

Derived itemized flow · Jul 29, 2024 to Oct 17, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Texas Trial Lawyers Association PAC$65,748.00

Texas Trial Lawyers Association PAC

$65,748.00

Cash
$32,500.00
Paid by others
$33,248.00
Total
$65,748.00
mail $33,248.00

Also funds 137 other sitting lawmakers.

Derived recipient stock · Jul 24, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Dec 10, 2024 to Oct 17, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100986461, 101011085, 101033172, 101044523, 101044526, 101072841.

Texas Sands PAC$58,000.00

Texas Sands PAC

$58,000.00

Cash
$58,000.00
Paid by others
$0.00
Total
$58,000.00

Also funds 121 other sitting lawmakers.

Derived recipient stock · Jul 3, 2024 to Oct 24, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Dec 10, 2024 to Feb 3, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100986461, 101044526.

Charter Schools Now PAC$36,000.00

Charter Schools Now PAC

$36,000.00

Cash
$1,000.00
Paid by others
$35,000.00
Total
$36,000.00
Other filed descriptions $35,000.00

Also funds 89 other sitting lawmakers.

Derived recipient stock · Oct 29, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Jan 22, 2026 to Feb 28, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101044523, 101061631.

Money

Missing data does not establish zero giving. Display amounts are rounded.

×

Texas Trial Lawyers Association PAC

$65,748.00

Cash
$32,500.00
Paid by others
$33,248.00
Total
$65,748.00
mail $33,248.00

Also funds 137 other sitting lawmakers.

Derived recipient stock · Jul 24, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Dec 10, 2024 to Oct 17, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100986461, 101011085, 101033172, 101044523, 101044526, 101072841.

×

Texas Sands PAC

$58,000.00

Cash
$58,000.00
Paid by others
$0.00
Total
$58,000.00

Also funds 121 other sitting lawmakers.

Derived recipient stock · Jul 3, 2024 to Oct 24, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Dec 10, 2024 to Feb 3, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100986461, 101044526.

×

Charter Schools Now PAC

$36,000.00

Cash
$1,000.00
Paid by others
$35,000.00
Total
$36,000.00
Other filed descriptions $35,000.00

Also funds 89 other sitting lawmakers.

Derived recipient stock · Oct 29, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Jan 22, 2026 to Feb 28, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101044523, 101061631.

Votes

No floor vote loaded for this bill.

Fiscal

No fiscal note in the loaded record.

How this was graded

Analysis of text version I by claude-opus-5-5, Oct 20, 2026, against the published rubric.

FILED BEFORE

Filed 2 times: 88R and 89R. Checked against 88R only.

88R HB 953

by Rep. Dutton, same lead author · Died in committee · same text

Introduced text

Last action, Mar 2, 2023: Referred to Ways & Means

Relating to a periodic review and expiration dates of state and local tax preferences.

Caption, 88R bill history

Sources

Texas House · Filed Feb 25, 2025

03/20/2025 H Referred to Ways & Means: Mar 20 2025 11:50AM

Texas Legislature Online · Introduced

Data snapshot Oct 26, 2026 at 4:19 AM CDT. Grades, charges, quotes and corrections follow the published record.

House committee · Ways & Means · Final status: Died in committee

Subjects

Governor

Legislature

State Agencies, Boards & Commissions--Newly Proposed

Taxation--General

Taxation--Property-Appraisals & Appraisal Districts

Taxation--Property-Assessment & Collection

Taxation--Property-Exemptions

Taxation--Property-Miscellaneous

LIEUTENANT GOVERNOR

SPEAKER OF THE HOUSE

COMPTROLLER OF PUBLIC ACCOUNTS

LEGISLATIVE BUDGET BOARD

LEGISLATIVE COUNCIL, TEXAS

PERIODIC TAX PREFERENCE REVIEW, SELECT COMMISSION ON (VV9M7)

Text

The text as introduced · 1,527 words

89R11812 SRA-D

By: Dutton
H.B. No. 3279

A BILL TO BE ENTITLED

AN ACT

relating to a periodic review and expiration dates of state and

local tax preferences.

BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF TEXAS:

SECTION 1. Subtitle B, Title 3, Government Code, is amended

by adding Chapter 320A to read as follows:

CHAPTER 320A. REVIEW OF STATE AND LOCAL TAX PREFERENCES

SUBCHAPTER A. GENERAL PROVISIONS

Sec. 320A.001. DEFINITIONS. In this chapter:

(1) "Commission" means the select commission on

periodic tax preference review.

(2) "Tax preference" means an abatement, credit,

discount, exclusion, exemption, limitation on appraised value,

refund, special valuation, special accounting treatment, special

appraisal method or provision, special rate, or special method of

reporting authorized by state law or the state constitution that

relates to a state or local tax imposed in this state.

SUBCHAPTER B. SELECT COMMISSION ON PERIODIC TAX PREFERENCE REVIEW

Sec. 320A.051. COMPOSITION OF COMMISSION. The select

commission on periodic tax preference review is composed of:

(1) five members of the house of representatives,

appointed by the speaker of the house of representatives;

(2) five members of the senate, appointed by the

lieutenant governor; and

(3) the comptroller.

Sec. 320A.052. TERMS. The members of the commission serve

two-year terms that expire December 31 of each even-numbered year.

Sec. 320A.053. VACANCY. If a vacancy occurs, the

individual who originally appointed the vacating member or the

individual's successor shall appoint an individual to fill the

vacancy for the remainder of the unexpired term.

Sec. 320A.054. OFFICERS. (a) The speaker of the house of

representatives shall select one member of the commission appointed

under Section 320A.051(1) to serve as chair of the commission.

(b) The lieutenant governor shall select one member of the

commission appointed under Section 320A.051(2) to serve as vice

chair of the commission.

Sec. 320A.055. MEETINGS. The commission shall meet at the

call of the chair.

Sec. 320A.056. STAFF. On the commission's request, the

Legislative Budget Board, the Texas Legislative Council, the office

of the governor, the comptroller, the senate, and the house of

representatives shall provide staff to assist the commission in

performing the commission's duties.

Sec. 320A.057. COOPERATION BY OTHER STATE ENTITIES. The

commission may request the assistance of any state agency,

department, or office if the commission needs assistance to perform

the commission's duties. The agency, department, or office shall

provide the requested assistance.

Sec. 320A.058. EXPENSES. The operating expenses of the

commission shall be paid from available funds of the office of the

governor and the contingent expense funds of the senate and the

house of representatives, as agreed by those entities. The

commission members are entitled to reimbursement from those funds

for expenses incurred by the members in implementing this chapter.

SUBCHAPTER C. POWERS AND DUTIES OF COMMISSION

Sec. 320A.101. DEVELOPMENT AND BIENNIAL MODIFICATION OF

STATE AND LOCAL TAX PREFERENCE REVIEW SCHEDULE. (a) The commission

shall:

(1) identify each state tax preference and each type

of local tax preference;

(2) develop a state and local tax preference review

schedule under which each identified tax preference is reviewed

once during each six-year period; and

(3) specifically identify on the schedule:

(A) each of the tax preferences the commission

must review for purposes of the next report due under Section

320A.153;

(B) any tax preference described by Paragraph (A)

that reduces by less than one-fourth of one percent the total

revenue derived from the tax to which the tax preference applies and

that the commission recommends for an abbreviated review; and

(C) the components of the review specified by

Section 320A.104 that the commission recommends are unnecessary

with respect to a tax preference recommended for an abbreviated

review.

(b) In developing the schedule, the commission shall

schedule the tax preferences for review in the order in which the

tax preferences were enacted or authorized, except that the

commission may schedule the initial review of a tax preference that

has an expiration date for any date the commission determines is

appropriate.

(c) The commission shall revise the schedule biennially

only to:

(1) add to the schedule a tax preference that was

enacted or authorized after the commission developed the most

recent schedule;

(2) delete from the schedule a tax preference that was

repealed after the commission developed the most recent schedule;

(3) update the review dates of the tax preferences for

which reviews were conducted after the commission developed the

most recent schedule; and

(4) update the tax preferences identified under

Subsection (a)(3).

Sec. 320A.102. PUBLIC COMMENT. The commission shall

provide a process by which the public may comment on the state and

local tax preference review schedule under Section 320A.101. The

commission shall consider those comments in developing or revising

the schedule.

Sec. 320A.103. COMPLETION OF SCHEDULE. The state and local

tax preference review schedule must be completed not later than

December 1 of each odd-numbered year.

Sec. 320A.104. PERIODIC REVIEW OF STATE AND LOCAL TAX

PREFERENCES. The commission shall review each state tax preference

and each type of local tax preference according to the state and

local tax preference review schedule developed under Section

320A.101. In reviewing a tax preference, the commission shall:

(1) determine the intended purpose of the tax

preference; and

(2) evaluate:

(A) whether the tax preference accomplishes its

intended purpose;

(B) whether the intended purpose of the tax

preference could be accomplished through a more cost-effective

method; and

(C) the effect of the tax preference on economic

development in this state.

SUBCHAPTER D. RECOMMENDATIONS REGARDING REVIEWED TAX PREFERENCES

Sec. 320A.151. PRELIMINARY REPORT. Not later than

September 1 of each even-numbered year, the commission shall file a

preliminary report on the reviews of tax preferences identified

under Section 320A.101(a)(3)(A) with the Senate Committee on

Finance or its successor and the House Committee on Ways and Means

or its successor. The report must include drafts of any proposed

legislation needed to implement the commission's recommendations.

Sec. 320A.152. REVIEW AND COMMENT. The Senate Committee on

Finance or its successor and the House Committee on Ways and Means

or its successor may review the preliminary report and proposed

legislation and submit comments to the commission. Comments must

be submitted not later than October 15 of each even-numbered year.

Sec. 320A.153. FINAL REPORT. (a) The commission may modify

the preliminary report and proposed legislation in response to the

comments received under Section 320A.152.

(b) Not later than December 1 of each even-numbered year,

the commission shall provide to the governor and the presiding

officers of the Senate Committee on Finance or its successor and the

House Committee on Ways and Means or its successor a final report on

the reviews of tax preferences identified under Section

320A.101(a)(3)(A) and proposed legislation necessary to implement

the commission's recommendations.

Sec. 320A.154. PUBLIC HEARING ON FINAL REPORT. The Senate

Committee on Finance or its successor and the House Committee on

Ways and Means or its successor shall hold a joint public hearing on

the final report and proposed legislation provided under Section

320A.153.

SUBCHAPTER E. EXPIRATION OF TAX PREFERENCES

Sec. 320A.201. EXPIRATION; REQUIRED STATEMENT. (a) A tax

preference included in a final report expires on the second

anniversary of the date the final report is submitted under Section

320A.153(b) unless reauthorized by law.

(b) Each tax preference enacted or reauthorized by an act of

the legislature that becomes law on or after September 1, 2026, must

state the expiration date of the preference and provide that the

preference expires on that date. The expiration date may not be

later than the sixth anniversary of the effective date of the law

enacting or most recently reauthorizing the tax preference.

(c) A tax preference to which Subsection (b) applies that

does not include the provision required by that subsection expires

on the sixth anniversary of the effective date of the law enacting

or most recently reauthorizing the preference.

SECTION 2. The lieutenant governor and the speaker of the

house of representatives shall appoint the initial members of the

select commission on periodic tax preference review not later than

January 5, 2026. Notwithstanding Section 320A.052, Government

Code, as added by this Act, the terms of the initial members of the

commission expire December 31, 2026.

SECTION 3. Notwithstanding Section 320A.103, Government

Code, as added by this Act, the select commission on periodic tax

preference review shall submit:

(1) the initial state and local tax preference review

schedule required by that section not later than January 15, 2026;

(2) the initial preliminary report required by Section

320A.151, Government Code, as added by this Act, not later than

September 1, 2026; and

(3) the initial final report required by Section

320A.153, Government Code, as added by this Act, not later than

December 1, 2026.

SECTION 4. This Act takes effect January 1, 2026, but only

if the constitutional amendment proposed by the 89th Legislature,

Regular Session, 2025, requiring the legislature to provide for a

periodic review of state and local tax preferences and providing

for the expiration of certain tax preferences after six years, or at

another time prescribed by the legislature, unless reauthorized by

law is approved by the voters. If that amendment is not approved by

the voters, this Act has no effect.