Monitoring the Session
HB 9

business personal property exemption jumps from $2,500 to $250,000

Became law

Verdict: No flags

No flagsInitial review
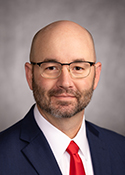
Rep. Morgan MeyerRHouse 108

Initial review · graded Oct 19, 2026 · Headline, summary and grade are analysis of the bill text, not a finding about any person · How we grade

Caption

relating to an exemption from ad valorem taxation of a portion of the appraised value of tangible personal property a person owns that is held or used for the production of income.

Caption from analyzed text · version I.

Summary

First $250,000 exempt, and no rendition filing below that line.

The bill raises the property tax exemption for business equipment, inventory and other income-producing personal property from items worth under $2,500 to the first $250,000 of value, and it excuses owners below that line from filing a rendition. It touches every business that owns taxable personal property, plus appraisal districts, tax assessors and local taxing units that must redo their rolls, rates and bills. The exemption only takes hold if voters approve a constitutional amendment at the November 4, 2025 election, and for 2025 tax bills go out as provisional, with a supplemental bill sent if the amendment fails.

Labels

Labels: ACROSS THE AISLE. Joint authors: 3 Republicans, 2 Democrats. Party as the Legislative Reference Library lists it for the 89th Legislature.

Receipt

The receipt

89R-HB9 · 2025-02-24

SOLD BY

+ 2 more authors, 71 coauthors

ITEM

relating to an exemption from ad valorem taxation of a portion of the appraised value of tangible personal property a person owns that is held or used for the production of income.

WHAT IT DOES

First $250,000 exempt, and no rendition filing below that line.

The bill raises the property tax exemption for business equipment, inventory and other income-producing personal property from items worth under $2,500 to the first $250,000 of value, and it excuses owners below that line from filing a rendition. It touches every business that owns taxable personal property, plus appraisal districts, tax assessors and local taxing units that must redo their rolls, rates and bills. The exemption only takes hold if voters approve a constitutional amendment at the November 4, 2025 election, and for 2025 tax bills go out as provisional, with a supplemental bill sent if the amendment fails.

CHARGES

[ ] NONE FOUND

TOTAL

Net to General Revenue · FY 2026$0

LBB estimate, flow · fiscal note version F · ( ) = negative · source

Sources

Fiscal note · version F · May 15, 2025

Estimated Two-year Net Impact to General Revenue Related Funds for HB9, As Passed 2nd House: a negative impact of ($193,504,000) through the biennium ending August 31, 2027.

First year · FY 2026 · $0

Probable Net Positive/(Negative) Impact to General Revenue Related Funds

LBB published estimates · flow over the stated periods.

Source snapshot 2026-10-19, Central time.

HISTORY

  1. Filed
  2. Read first time
  3. Referred to Ways & Means
  4. Posting rule suspended
  5. Scheduled for public hearing on . . .
  6. Considered in public hearing
  7. Testimony taken/registration(s) recorded in committee
  8. Left pending in committee
  9. Considered in public hearing
  10. Reported favorably w/o amendment(s)
  11. Comte report filed with Committee Coordinator
  12. Committee report distributed
  13. Committee report sent to Calendars
  14. Considered in Calendars
  15. Placed on General State Calendar
  16. Read 2nd time
  17. Passed to engrossment
  18. Record vote RV#68
  19. Statement(s) of vote recorded in Journal
  20. Read 3rd time
  21. Passed
  22. Record vote RV#72
  23. Reported engrossed
  24. Received from the House
  25. Read first time
  26. Referred to Local Government
  27. Scheduled for public hearing on . . .
  28. Considered in public hearing
  29. Testimony taken in committee
  30. Vote taken in committee
  31. Reported favorably as substituted
  32. Committee report printed and distributed
  33. Co-sponsor authorized
  34. Placed on intent calendar
  35. Co-sponsor authorized
  36. Rules suspended-Regular order of business
  37. Read 2nd time
  38. Amendment(s) offered FA1 Bettencourt
  39. Amended
  40. Vote recorded in Journal
  41. Passed to 3rd reading as amended
  42. Vote recorded in Journal
  43. Three day rule suspended
  44. Record vote
  45. Read 3rd time
  46. Passed
  47. Record vote
  48. Senate passage as amended reported
  49. Senate Amendments distributed
  50. Senate Amendments Analysis distributed
  51. House concurs in Senate amendment(s)
  52. Record vote RV#2999
  53. Statement(s) of vote recorded in Journal
  54. Text of Senate Amendment(s)
  55. House concurs in Senate amendment(s)-reported
  56. Reported enrolled
  57. Signed in the House
  58. Signed in the Senate
  59. Sent to the Governor
  60. Signed by the Governor
  61. See remarks for effective date
FILED UNDER

No verified beat found.

SIGNED FOR BY

House · 133 yea · 10 nay

Senate · 31 yea · 0 nay

Sources

House: Final passage · Apr 3, 2025. Journal. Published stock for this vote. Snapshot 2026-10-19, Central time.

Senate: Final passage · May 14, 2025. Journal. Published stock for this vote. Snapshot 2026-10-19, Central time.

All floor motions and other positions below.

No flags

THANK YOU FOR CHECKING THE RECEIPT

CAMPAIGN PAID FOR BY

CAMPAIGN PAID FOR BY

Donors

Not tied to this bill.

Sources

The author's campaign account only. Own money and internal transfers are separate on the member page.

Derived itemized flow · Oct 28, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Texans for Lawsuit Reform PAC$530,160.35

Texans for Lawsuit Reform PAC

$530,160.35

Cash
$275,000.00
Paid by others
$255,160.35
Total
$530,160.35
advertising $220,000.00polling $35,160.35

Also funds 124 other sitting lawmakers.

Derived recipient stock · Jul 10, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Jun 23, 2025 to Oct 16, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101012321, 101035164, 101040580, 101060247, 101069424, 101072232.

Texas Conservative Majority PAC$422,350.00

Texas Conservative Majority PAC

$422,350.00

Cash
$150,000.00
Paid by others
$272,350.00
Total
$422,350.00
canvassing $250,000.00polling $22,350.00

Also funds 42 other sitting lawmakers.

Derived recipient stock · Jan 23, 2026 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Feb 18, 2026 to Oct 23, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101040580, 101069424, 101072232.

Texas Sands PAC$262,000.00

Texas Sands PAC

$262,000.00

Cash
$262,000.00
Paid by others
$0.00
Total
$262,000.00

Also funds 121 other sitting lawmakers.

Derived recipient stock · Jul 3, 2024 to Oct 24, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Nov 13, 2024 to Sep 25, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100988696, 101040580, 101072232.

Money

Missing data does not establish zero giving. Display amounts are rounded.

×

Texans for Lawsuit Reform PAC

$530,160.35

Cash
$275,000.00
Paid by others
$255,160.35
Total
$530,160.35
advertising $220,000.00polling $35,160.35

Also funds 124 other sitting lawmakers.

Derived recipient stock · Jul 10, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Jun 23, 2025 to Oct 16, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101012321, 101035164, 101040580, 101060247, 101069424, 101072232.

×

Texas Conservative Majority PAC

$422,350.00

Cash
$150,000.00
Paid by others
$272,350.00
Total
$422,350.00
canvassing $250,000.00polling $22,350.00

Also funds 42 other sitting lawmakers.

Derived recipient stock · Jan 23, 2026 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Feb 18, 2026 to Oct 23, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101040580, 101069424, 101072232.

×

Texas Sands PAC

$262,000.00

Cash
$262,000.00
Paid by others
$0.00
Total
$262,000.00

Also funds 121 other sitting lawmakers.

Derived recipient stock · Jul 3, 2024 to Oct 24, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Nov 13, 2024 to Sep 25, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100988696, 101040580, 101072232.

Votes6

House May 19, 2025

Yea
110
Nay
15
Present, not voting
1
Absent
7
Excused
17
Names

Named positions matched to lawmakers. See the journal for unmatched names.

House journal

Sources

Record 2999

Representative Meyer moved to concur in the senate amendments to HB 9. The motion to concur in the senate amendments to HB 9 prevailed by (Record 2999): 110 Yeas, 15 Nays, 1 Present, not voting.

Published stock of positions for this vote, except where marked derived.

  • Yea: 110 (published)
  • Nay: 15 (published)
  • Present, not voting: 1 (published)
  • Absent: 7 (derived from named list)
  • Excused: 17 (derived from named list)

House journal. Source snapshot 2026-10-19, Central time.

Senate May 14, 2025

Yea
31
Nay
0
Present, not voting
Not printed
Absent
Not printed
Excused
Not printed
Names

Senate journal

Names were not printed. No individual positions are inferred.

Sources

Senator Bettencourt moved that Senate Rule 7.18 and the Constitutional Rule requiring bills to be read on three several days be suspended and that CSHB 9 be placed on its third reading and final passage. The motion prevailed by the following vote: Yeas 31, Nays 0. The bill was read third time and was passed by the following vote: Yeas 31, Nays 0.

Published stock of positions for this vote, except where marked derived.

  • Yea: 31 (published)
  • Nay: 0 (published)
  • Present, not voting: Not printed
  • Absent: Not printed
  • Excused: Not printed

Senate journal. Source snapshot 2026-10-19, Central time.

Senate May 14, 2025

Yea
31
Nay
0
Present, not voting
Not printed
Absent
Not printed
Excused
Not printed
Names

Senate journal

Names were not printed. No individual positions are inferred.

Sources

Senator Bettencourt moved that Senate Rule 7.18 and the Constitutional Rule requiring bills to be read on three several days be suspended and that CSHB 9 be placed on its third reading and final passage. The motion prevailed by the following vote: Yeas 31, Nays 0.

Published stock of positions for this vote, except where marked derived.

  • Yea: 31 (published)
  • Nay: 0 (published)
  • Present, not voting: Not printed
  • Absent: Not printed
  • Excused: Not printed

Senate journal. Source snapshot 2026-10-19, Central time.

Senate May 14, 2025

Yea
Not printed
Nay
Not printed
Present, not voting
Not printed
Absent
Not printed
Excused
Not printed
Names

Senate journal

Names were not printed. No individual positions are inferred.

Voice vote. No numeric tally or individual yeas are inferred.

Sources

CSHB 9 as amended was passed to third reading by a viva voce vote.

Published stock of positions for this vote, except where marked derived.

  • Yea: Not printed
  • Nay: Not printed
  • Present, not voting: Not printed
  • Absent: Not printed
  • Excused: Not printed

Senate journal. Source snapshot 2026-10-19, Central time.

House Apr 3, 2025

Yea
133
Nay
10
Present, not voting
2
Absent
2
Excused
3
Names

Named positions matched to lawmakers. See the journal for unmatched names.

House journal

Sources

Record 72

HB 9 was passed by (Record 72): 133 Yeas, 10 Nays, 2 Present, not voting.

Published stock of positions for this vote, except where marked derived.

  • Yea: 133 (published)
  • Nay: 10 (published)
  • Present, not voting: 2 (published)
  • Absent: 2 (derived from named list)
  • Excused: 3 (derived from named list)

House journal. Source snapshot 2026-10-19, Central time.

House Apr 2, 2025

Yea
132
Nay
12
Present, not voting
1
Absent
3
Excused
2
Names

Named positions matched to lawmakers. See the journal for unmatched names.

House journal

Sources

Record 68

HB 9 was passed to engrossment by (Record 68): 132 Yeas, 12 Nays, 1 Present, not voting.

Published stock of positions for this vote, except where marked derived.

  • Yea: 132 (published)
  • Nay: 12 (published)
  • Present, not voting: 1 (published)
  • Absent: 3 (derived from named list)
  • Excused: 2 (derived from named list)

House journal. Source snapshot 2026-10-19, Central time.

Witnesses44
For
33
Against
5
On
6
Names

For

  • AT&T2 registrations
  • Huffines Libert Foundation1 registration
  • NFIB2 registrations
  • Panhandle Producers & Royalty Owners Association1 registration
  • Self1 registration
  • Self; Americans for Prosperity1 registration
  • Self; Americans for prosperity1 registration
  • Self; Restaurant Mixtli1 registration
  • Self; South Texans’ Property Rights Association1 registration
  • Self; The LIBRE Initiative1 registration
  • Texas Apartment Association1 registration
  • Texas Association of Builders1 registration
  • Texas Association of Business2 registrations
  • Texas Association of Manufacturers, Texas Chemistry Council, Texas Oil and Gas Association1 registration
  • Texas Association of Property Tax Professionals1 registration
  • Texas Farm Bureau2 registrations
  • Texas Forestry Association1 registration
  • Texas Hotel and Lodging Association1 registration
  • Texas Oil & Gas Association, Texas Chemistry Council, Texas Association of Manufacturers1 registration
  • Texas Package Stores Association1 registration
  • Texas REALTORS1 registration
  • Texas Realtors1 registration
  • Texas Restaurant Association1 registration
  • Texas Retailers Association2 registrations
  • Texas Taxpayers and Research Association2 registrations
  • Wholesale Beer Distributors of Texas2 registrations

Against

  • City of Austin1 registration
  • El Paso County1 registration
  • Harris County Commissioners Court1 registration
  • Self1 registration
  • Travis County Commissioners Court1 registration

On

  • City of Fort Worth1 registration
  • City of San Antonio1 registration
  • Comptroller of Public Accounts2 registrations
  • Conference ofUrban Counties1 registration
  • Self; County Judge, County Judges and Commissioners Association of Texas1 registration
Sources

44 parsed registrations across the loaded witness lists.

Derived stock of witness registrations. Repeated appearances count separately. Organizations and self-representation appear as printed.

House witness list. Source snapshot 2026-10-20, Central time.

Senate witness list. Source snapshot 2026-10-20, Central time.

Fiscal
Net to General Revenue · FY 2026$0

LBB estimate, flow · fiscal note version F · ( ) = negative · source

Sources

Fiscal note · version F · May 15, 2025

Estimated Two-year Net Impact to General Revenue Related Funds for HB9, As Passed 2nd House: a negative impact of ($193,504,000) through the biennium ending August 31, 2027.

First year · FY 2026 · $0

Probable Net Positive/(Negative) Impact to General Revenue Related Funds

LBB published estimates · flow over the stated periods.

Source snapshot 2026-10-19, Central time.

How this was graded

Analysis of text version I by claude-opus-5-5, Oct 19, 2026, against the published rubric.

Sources

Texas House · Filed Feb 24, 2025

06/12/2025 E See remarks for effective date

Texas Legislature Online · Introduced · House Committee Report · Engrossed · Senate Committee Report · Enrolled

Data snapshot Oct 26, 2026 at 4:20 AM CDT. Grades, charges, quotes and corrections follow the published record.

Coauthors
Daniel AldersRHouse 6 Trent AshbyRHouse 9 Jeff BarryRHouse 29 Cecil Bell Jr.RHouse 3 Keith BellRHouse 4 Brad BuckleyRHouse 54 Benjamin BumgarnerRHouse 63 Angie Chen ButtonRHouse 112 Giovanni CapriglioneRHouse 98 David CookRHouse 96 Philip CortezDHouse 117 Tom CraddickRHouse 82 Charles CunninghamRHouse 127 Pat CurryRHouse 56 Aicha DavisDHouse 109 Jay DeanRHouse 7 Mano DeAyalaRHouse 133 Mark DorazioRHouse 122 Paul DysonRHouse 14 Caroline FairlyRHouse 87 James FrankRHouse 69 Cassandra Garcia HernandezDHouse 115 Gary GatesRHouse 28 Stan GerdesRHouse 17 Charlie GerenRHouse 99 Ryan GuillenRHouse 31 Sam HarlessRHouse 126 Cody HarrisRHouse 8 Caroline Harris DavilaRHouse 52 Richard HayesRHouse 57 Cole HefnerRHouse 5 Lacey HullRHouse 138 Carrie IsaacRHouse 73 Helen KerwinRHouse 58 Stan KitzmanRHouse 85 Stan LambertRHouse 71 Brooks LandgrafRHouse 81 Jeff LeachRHouse 67 Terri Leo WilsonRHouse 23 Janie LopezRHouse 37 Ray LopezDHouse 125 John LujanRHouse 118 Shelley LutherRHouse 62 Armando "Mando" MartinezDHouse 39 John McQueeneyRHouse 97 Will MetcalfRHouse 16 Brent MoneyRHouse 2 Matt MorganRHouse 26 Sergio Muñoz Jr.DHouse 36 Candy NobleRHouse 89 Tom OliversonRHouse 130 Angelia OrrRHouse 13 Jared PattersonRHouse 106 Dennis PaulRHouse 129 Katrina PiersonRHouse 33 Mihaela PlesaDHouse 70 Richard Peña RaymondDHouse 42 Keresa RichardsonRHouse 61 Mike SchofieldRHouse 132 Matt ShaheenRHouse 66 Joanne ShofnerRHouse 11 Shelby SlawsonRHouse 59 David SpillerRHouse 68 Valoree SwansonRHouse 150 Carl H. TepperRHouse 84 Tony TinderholtRHouse 94 Ellen TroxclairRHouse 19 Gary VanDeaverRHouse 1 Cody VasutRHouse 25 Trey WhartonRHouse 12 Terry M. WilsonRHouse 20
Sponsors
Cosponsors

House committee · Ways & Means · Committee vote 12 aye, 0 nay, 1 absent · Out of committee

Senate committee · Local Government · Committee vote 7 aye, 0 nay · Out of committee

Enabling legislation for HJR 1.

Subjects

Business & Commerce--General

City Government--Employees/Officers

County Government--Employees/Officers

Property Interests--Personal Property

Taxation--Property-Appraisals & Appraisal Districts

Taxation--Property-Exemptions

Taxation--Property-Tax Rate

Taxation--School District

COUNTY TAX ASSESSOR-COLLECTORS

Text

The text as introduced · 2,363 words

89R14621 TJB-D

By: Meyer
H.B. No. 9

A BILL TO BE ENTITLED

AN ACT

relating to an exemption from ad valorem taxation of a portion of

the appraised value of tangible personal property a person owns

that is held or used for the production of income.

BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF TEXAS:

ARTICLE 1. PROVISIONS CONTINGENT ON CONSTITUTIONAL AMENDMENT

SECTION 1.01. The heading to Section 11.145, Tax Code, is

amended to read as follows:

Sec. 11.145. INCOME-PRODUCING TANGIBLE PERSONAL PROPERTY

[ HAVING VALUE OF LESS THAN $2,500 ].

SECTION 1.02. Section 11.145(a), Tax Code, is amended to

read as follows:

(a) A person is entitled to an exemption from taxation of

$250,000 of the appraised value of tangible personal property the

person owns that is held or used for the production of income [ if

that property has a taxable value of less than $2,500 ].

SECTION 1.03. Section 22.01, Tax Code, is amended by adding

Subsection (j-1) to read as follows:

(j-1) A person is required to render tangible personal

property the person owns that is held or used for the production of

income only if, in the person's opinion, the aggregate market value

of the property in at least one taxing unit that participates in the

appraisal district is greater than the amount exempted under

Section 11.145(a). A person required to render property for

taxation under this subsection must render all tangible personal

property the person owns that is held or used for the production of

income and has taxable situs in the appraisal district. This

subsection does not apply to property exempt from taxation under a

provision of law other than Section 11.145.

SECTION 1.04. The changes in law made by this article apply

only to an ad valorem tax year that begins on or after January 1,

2025.

ARTICLE 2. PROVISIONS NOT CONTINGENT ON CONSTITUTIONAL AMENDMENT

SECTION 2.01. Section 26.01, Tax Code, is amended by adding

Subsections (a-2) and (a-3) to read as follows:

(a-2) This subsection applies only to the appraisal roll for

a taxing unit for the 2025 tax year. When the chief appraiser

delivers the appraisal roll to the assessor for the taxing unit, the

chief appraiser shall include a provisional appraisal roll to

account for the changes in law attributable to the constitutional

amendment proposed by the 89th Legislature, Regular Session, 2025,

to authorize the legislature to exempt from ad valorem taxation a

portion of the market value of tangible personal property a person

owns that is held or used for the production of income, as if those

changes were in effect. If the chief appraiser delivers a

supplemental appraisal roll or correction to the appraisal roll to

the assessor for the taxing unit before that constitutional

amendment takes effect, the chief appraiser shall include

provisional appraisal roll entries to account for the changes in

law attributable to that constitutional amendment. If that

constitutional amendment takes effect:

(1) on the date that constitutional amendment takes

effect, the provisional appraisal roll, as supplemented and

corrected, becomes the appraisal roll for the taxing unit; and

(2) as soon as practicable after that date, the chief

appraiser shall correct the taxing unit's appraisal roll as

necessary to finally account for the changes in law attributable to

that constitutional amendment.

(a-3) This subsection and Subsection (a-2) expire December

31, 2026.

SECTION 2.02. Section 26.04, Tax Code, is amended by adding

Subsections (a-1) and (c-1) to read as follows:

(a-1) On receipt of the appraisal roll for the 2025 tax

year, the assessor for a taxing unit shall determine the total

taxable value of property taxable by the taxing unit and the taxable

value of new property as if the changes in law attributable to the

constitutional amendment proposed by the 89th Legislature, Regular

Session, 2025, to authorize the legislature to exempt from ad

valorem taxation a portion of the market value of tangible personal

property a person owns that is held or used for the production of

income were in effect for that tax year. This subsection expires

December 31, 2026.

(c-1) An officer or employee designated by the governing

body of a taxing unit shall calculate the no-new-revenue tax rate

and the voter-approval tax rate of the taxing unit for the 2025 tax

year as if the changes in law attributable to the constitutional

amendment proposed by the 89th Legislature, Regular Session, 2025,

to authorize the legislature to exempt from ad valorem taxation a

portion of the market value of tangible personal property a person

owns that is held or used for the production of income were in

effect for that tax year. This subsection expires December 31,

2026.

SECTION 2.03. Chapter 26, Tax Code, is amended by adding

Section 26.0401 to read as follows:

Sec. 26.0401. CALCULATION OF CERTAIN TAX RATES FOR 2025 TAX

YEAR. (a) For the purposes of calculating the no-new-revenue tax

rate, the voter-approval tax rate, and any related tax rate for the

2025 tax year, a taxing unit that calculates those rates under a

provision of law other than Section 26.04 or 26.08 shall calculate

those rates as if the changes in law attributable to the

constitutional amendment proposed by the 89th Legislature, Regular

Session, 2025, to authorize the legislature to exempt from ad

valorem taxation a portion of the market value of tangible personal

property a person owns that is held or used for the production of

income were in effect for that tax year.

(b) This section expires December 31, 2026.

SECTION 2.04. Section 26.08, Tax Code, is amended by adding

Subsection (q) to read as follows:

(q) For purposes of this section, the voter-approval tax

rate of a school district for the 2025 tax year shall be calculated

as if the changes in law attributable to the constitutional

amendment proposed by the 89th Legislature, Regular Session, 2025,

to authorize the legislature to exempt from ad valorem taxation a

portion of the market value of tangible personal property a person

owns that is held or used for the production of income were in

effect for that tax year. This subsection expires December 31,

2026.

SECTION 2.05. Section 26.09, Tax Code, is amended by adding

Subsection (c-1) to read as follows:

(c-1) The assessor for a taxing unit shall calculate the

amount of tax imposed by the taxing unit on the tangible personal

property a person owns that is held or used for the production of

income for the 2025 tax year as if the changes in law attributable

to the constitutional amendment proposed by the 89th Legislature,

Regular Session, 2025, to authorize the legislature to exempt from

ad valorem taxation a portion of the market value of tangible

personal property a person owns that is held or used for the

production of income were in effect for that tax year and also as if

the changes in law attributable to that constitutional amendment

were not in effect for that tax year. This subsection expires

December 31, 2026.

SECTION 2.06. Section 26.15, Tax Code, is amended by adding

Subsection (h) to read as follows:

(h) The assessor for a taxing unit shall correct the tax

roll for the taxing unit for the 2025 tax year to reflect the

results of the election to approve the constitutional amendment

proposed by the 89th Legislature, Regular Session, 2025, to

authorize the legislature to exempt from ad valorem taxation a

portion of the market value of tangible personal property a person

owns that is held or used for the production of income. This

subsection expires December 31, 2026.

SECTION 2.07. Section 31.01, Tax Code, is amended by adding

Subsections (d-2), (d-3), (d-4), and (d-5) to read as follows:

(d-2) This subsection and Subsections (d-3) and (d-4) apply

only to taxes imposed by a taxing unit on the tangible personal

property a person owns that is held or used for the production of

income for the 2025 tax year and only if the changes in law

attributable to the constitutional amendment proposed by the 89th

Legislature, Regular Session, 2025, to authorize the legislature to

exempt from ad valorem taxation a portion of the market value of

tangible personal property a person owns that is held or used for

the production of income would lower the taxes imposed by the taxing

unit on the property for that tax year. The assessor for the taxing

unit shall compute the amount of taxes imposed and the other

information required by this section as if the changes in law

attributable to that constitutional amendment were in effect for

that tax year. The tax bill or the separate statement must indicate

that the bill is a provisional tax bill and include a statement in

substantially the following form:

"If the Texas Legislature had not enacted property tax relief

legislation during the 2025 legislative session, your tax bill

would have been $____ (insert amount of tax bill if the changes in

law attributable to the constitutional amendment proposed by the

89th Legislature, Regular Session, 2025, to authorize the

legislature to exempt from ad valorem taxation a portion of the

market value of tangible personal property a person owns that is

held or used for the production of income were not in effect for

that tax year). Because of action by the Texas Legislature, your

tax bill has been lowered by $____ (insert difference between

amount of tax bill if the changes in law attributable to that

constitutional amendment were not in effect for that tax year and

amount of tax bill if the changes in law attributable to that

constitutional amendment were in effect for that tax year),

resulting in a lower tax bill of $____ (insert amount of tax bill if

the changes in law attributable to that constitutional amendment

were in effect for that tax year), contingent on the approval by the

voters at an election to be held November 4, 2025, of the

constitutional amendment proposed by the 89th Legislature, Regular

Session, 2025, to authorize the legislature to exempt from ad

valorem taxation a portion of the market value of tangible personal

property a person owns that is held or used for the production of

income. If that constitutional amendment is not approved by the

voters at the election, a supplemental tax bill in the amount of

$____ (insert difference between amount of tax bill if the changes

in law attributable to that constitutional amendment were not in

effect for that tax year and amount of tax bill if the changes in law

attributable to that constitutional amendment were in effect for

that tax year) will be mailed to you."

(d-3) A tax bill prepared by the assessor for a taxing unit

as provided by Subsection (d-2) and mailed as provided by

Subsection (a) is considered to be a provisional tax bill until the

canvass of the votes on the constitutional amendment proposed by

the 89th Legislature, Regular Session, 2025, to authorize the

legislature to exempt from ad valorem taxation a portion of the

market value of tangible personal property a person owns that is

held or used for the production of income. If that constitutional

amendment is approved by the voters, the tax bill is considered to

be a final tax bill for the taxes imposed on the property for the

2025 tax year, and no additional tax bill is required to be mailed

unless another provision of this title requires the mailing of a

corrected tax bill. If that constitutional amendment is not

approved by the voters:

(1) a tax bill prepared by the assessor as provided by

Subsection (d-2) is considered to be a final tax bill but only as to

the portion of the taxes imposed on the property for the 2025 tax

year that is included in the bill;

(2) the amount of taxes imposed by each taxing unit on

the tangible personal property a person owns that is held or used

for the production of income for the 2025 tax year is calculated as

if the changes in law attributable to that constitutional amendment

were not in effect for that tax year; and

(3) except as provided by Subsections (f), (i-1), and

(k), the assessor for each taxing unit shall prepare and mail a

supplemental tax bill, by December 1 or as soon thereafter as

practicable, in an amount equal to the difference between the

amount of the tax bill if the changes in law attributable to that

constitutional amendment were not in effect for that tax year and

the amount of the tax bill if the changes in law attributable to

that constitutional amendment were in effect for that tax year.

(d-4) Except as otherwise provided by Subsection (d-3), the

provisions of this section other than Subsection (d-2) apply to a

supplemental tax bill mailed under Subsection (d-3).

(d-5) This subsection and Subsections (d-2), (d-3), and

(d-4) expire December 31, 2026.

SECTION 2.08. Section 31.02, Tax Code, is amended by adding

Subsection (a-1) to read as follows:

(a-1) Except as provided by Subsection (b) of this section

and Sections 31.03 and 31.04, taxes for which a supplemental tax

bill is mailed under Section 31.01(d-3) are due on receipt of the

tax bill and are delinquent if not paid before March 1 of the year

following the year in which imposed. This subsection expires

December 31, 2026.

ARTICLE 3. EFFECTIVE DATES

SECTION 3.01. Except as otherwise provided by this article:

(1) this Act takes effect immediately if this Act

receives a vote of two-thirds of all the members elected to each

house, as provided by Section 39, Article III, Texas Constitution;

and

(2) if this Act does not receive the vote necessary for

immediate effect, this Act takes effect September 1, 2025.

SECTION 3.02. Article 1 of this Act takes effect on the date

on which the constitutional amendment proposed by the 89th

Legislature, Regular Session, 2025, to authorize the legislature to

exempt from ad valorem taxation a portion of the market value of

tangible personal property a person owns that is held or used for

the production of income takes effect. If that amendment is not

approved by the voters, Article 1 of this Act has no effect.