Monitoring the Session

HB 885

bill to stop taxing ramps and accessible features

Filed

Verdict: No flags

No flagsInitial review
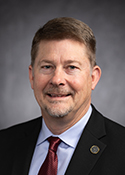
Rep. Trey WhartonRHouse 12

Initial review · graded Nov 9, 2026 · How we grade

Caption

relating to the exclusion from the market value of real property for ad valorem tax purposes of the value of any improvement, or any feature incorporated in an improvement, made to the property if the primary purpose of the improvement or feature is compliance with the requirements of standards that address accessible design of buildings or other facilities.

Caption from analyzed text · version I.

Summary

Accessibility upgrades leave the appraisal, starting 2028 if voters agree.

The bill tells county appraisers to leave out the value of any building change or feature made mainly to meet federal disability-access design standards when they set a property's taxable market value. It touches any property owner who adds things like ramps or accessible features on or after January 1, 2027. If voters approve a matching constitutional amendment, those owners will not pay property tax on that added value starting with the 2028 tax year.

Labels

Labels: ZOMBIE BILL. Died 2 times: 88R HB 543 by Rep. Raymond (Died in committee) and 89R HB 1547 by Rep. Raymond (Did not pass). Checked against 88R and 89R only.BACK FROM THE DEAD. Same text as a bill filed before that died: 88R HB 543 by Rep. Raymond (Died in committee) and 89R HB 1547 by Rep. Raymond (Did not pass). Filed in 3 sessions, counting this one. Checked against 88R and 89R only.TRY NO. 3. Filed in 3 sessions: 88R, 89R and 90R. Checked against 88R and 89R only.

Receipt

The receipt

90R-HB885 · 2026-11-09

SOLD BY

ITEM

relating to the exclusion from the market value of real property for ad valorem tax purposes of the value of any improvement, or any feature incorporated in an improvement, made to the property if the primary purpose of the improvement or feature is compliance with the requirements of standards that address accessible design of buildings or other facilities.

WHAT IT DOES

Accessibility upgrades leave the appraisal, starting 2028 if voters agree.

The bill tells county appraisers to leave out the value of any building change or feature made mainly to meet federal disability-access design standards when they set a property's taxable market value. It touches any property owner who adds things like ramps or accessible features on or after January 1, 2027. If voters approve a matching constitutional amendment, those owners will not pay property tax on that added value starting with the 2028 tax year.

CHARGES

[ ] NONE FOUND

TOTAL

No fiscal note in the loaded record.

HISTORY

  1. Filed
FILED UNDER

No verified beat found.

No flags

THANK YOU FOR CHECKING THE RECEIPT

CAMPAIGN PAID FOR BY

CAMPAIGN PAID FOR BY

Donors

Not tied to this bill.

Sources

The author's campaign account only. Own money and internal transfers are separate on the member page.

Derived itemized flow · Oct 27, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Texans for Lawsuit Reform PAC$20,000.00

Texans for Lawsuit Reform PAC

$20,000.00

Cash
$20,000.00
Paid by others
$0.00
Total
$20,000.00

Also funds 124 other sitting lawmakers.

Derived recipient stock · Jul 10, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Jun 30, 2025 to Oct 19, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101004685, 101026029, 101071395.

Texas Sands PAC$12,000.00

Texas Sands PAC

$12,000.00

Cash
$12,000.00
Paid by others
$0.00
Total
$12,000.00

Also funds 121 other sitting lawmakers.

Derived recipient stock · Jul 3, 2024 to Oct 24, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Dec 12, 2024 to Oct 19, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100981751, 101056205, 101071395.

Clint McLaren$7,205.31
Money

Missing data does not establish zero giving. Display amounts are rounded.

×

Texans for Lawsuit Reform PAC

$20,000.00

Cash
$20,000.00
Paid by others
$0.00
Total
$20,000.00

Also funds 124 other sitting lawmakers.

Derived recipient stock · Jul 10, 2024 to Oct 23, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Jun 30, 2025 to Oct 19, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 101004685, 101026029, 101071395.

×

Texas Sands PAC

$12,000.00

Cash
$12,000.00
Paid by others
$0.00
Total
$12,000.00

Also funds 121 other sitting lawmakers.

Derived recipient stock · Jul 3, 2024 to Oct 24, 2026. State data as of Nov 4, 2026.

TEC account match.

Team
Sources

Derived itemized flow · Dec 12, 2024 to Oct 19, 2026. State data as of Nov 4, 2026.

Derived itemized contributions on live regular reports and uncovered special-session dates. Internal account transfers and daily reports are excluded.

Report IDs: 100981751, 101056205, 101071395.

Votes

No floor vote loaded for this bill.

Fiscal

No fiscal note in the loaded record.

How this was graded

Analysis of text version I by a super-expensive superintelligence, Nov 9, 2026, against the published rubric.

FILED BEFORE

Filed 3 times: 88R, 89R and now. Checked against 88R and 89R only.

88R HB 543

by Rep. Raymond, different lead author · Died in committee · same text

Introduced text

Last action, Feb 23, 2023: Referred to Ways & Means

Relating to the exclusion from the market value of real property for ad valorem tax purposes of the value of any improvement, or any feature incorporated in an improvement, made to the property if the primary purpose of the improvement or feature is compliance with the requirements of standards that address accessible design of buildings or other facilities.

Caption, 88R bill history

89R HB 1547

by Rep. Raymond, different lead author · Did not pass · same text

Introduced text

Last action, Apr 8, 2025: Reported from s/c favorably w/o amendment(s)

Relating to the exclusion from the market value of real property for ad valorem tax purposes of the value of any improvement, or any feature incorporated in an improvement, made to the property if the primary purpose of the improvement or feature is compliance with the requirements of standards that address accessible design of buildings or other facilities.

Caption, 89R bill history

Sources

Texas House · Filed Nov 9, 2026

11/09/2026 H Filed

Texas Legislature Online · Introduced

Data snapshot Nov 10, 2026 at 2:37 AM CST. Grades, charges, quotes and corrections follow the published record.

Subjects

Disabilities, Persons with

Taxation--Property-Appraisals & Appraisal Districts

Taxation--Property-Exemptions

Text

The text as introduced · 401 words

90R3547 SZA-D

By: Wharton
H.B. No. 885

A BILL TO BE ENTITLED

AN ACT

relating to the exclusion from the market value of real property for

ad valorem tax purposes of the value of any improvement, or any

feature incorporated in an improvement, made to the property if the

primary purpose of the improvement or feature is compliance with

the requirements of standards that address accessible design of

buildings or other facilities.

BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF TEXAS:

SECTION 1. Subchapter A, Chapter 23, Tax Code, is amended by

adding Section 23.015 to read as follows:

Sec. 23.015. EXCLUSION OF VALUE OF IMPROVEMENT MADE TO

COMPLY WITH ACCESSIBILITY STANDARDS. In determining the market

value of real property, the chief appraiser shall exclude from that

value the value of any improvement, or any feature incorporated in

an improvement, made to the property if the primary purpose of the

improvement or feature is compliance with the requirements of the

2010 Americans with Disabilities Act Standards for Accessible

Design or any successor standards that address accessible design of

buildings or other facilities and are promulgated under the

Americans with Disabilities Act of 1990 (42 U.S.C. Section 12101 et

seq.).

SECTION 2. This Act applies only to the determination of the

market value of real property for ad valorem tax purposes for a tax

year that begins on or after the effective date of this Act.

SECTION 3. The change in law made by this Act applies to an

improvement, or a feature incorporated in an improvement, described

by Section 23.015, Tax Code, as added by this Act, made to real

property only if the improvement is made to the property, or the

feature is incorporated in an improvement made to the property, on

or after January 1, 2027.

SECTION 4. This Act takes effect January 1, 2028, but only

if the constitutional amendment proposed by the 90th Legislature,

Regular Session, 2027, to authorize the legislature to exclude from

the market value of real property for ad valorem tax purposes the

value of any improvement, or any feature incorporated in an

improvement, made to the property if the primary purpose of the

improvement or feature is compliance with the requirements of

standards that address accessible design of buildings or other

facilities is approved by the voters. If that amendment is not

approved by the voters, this Act has no effect.